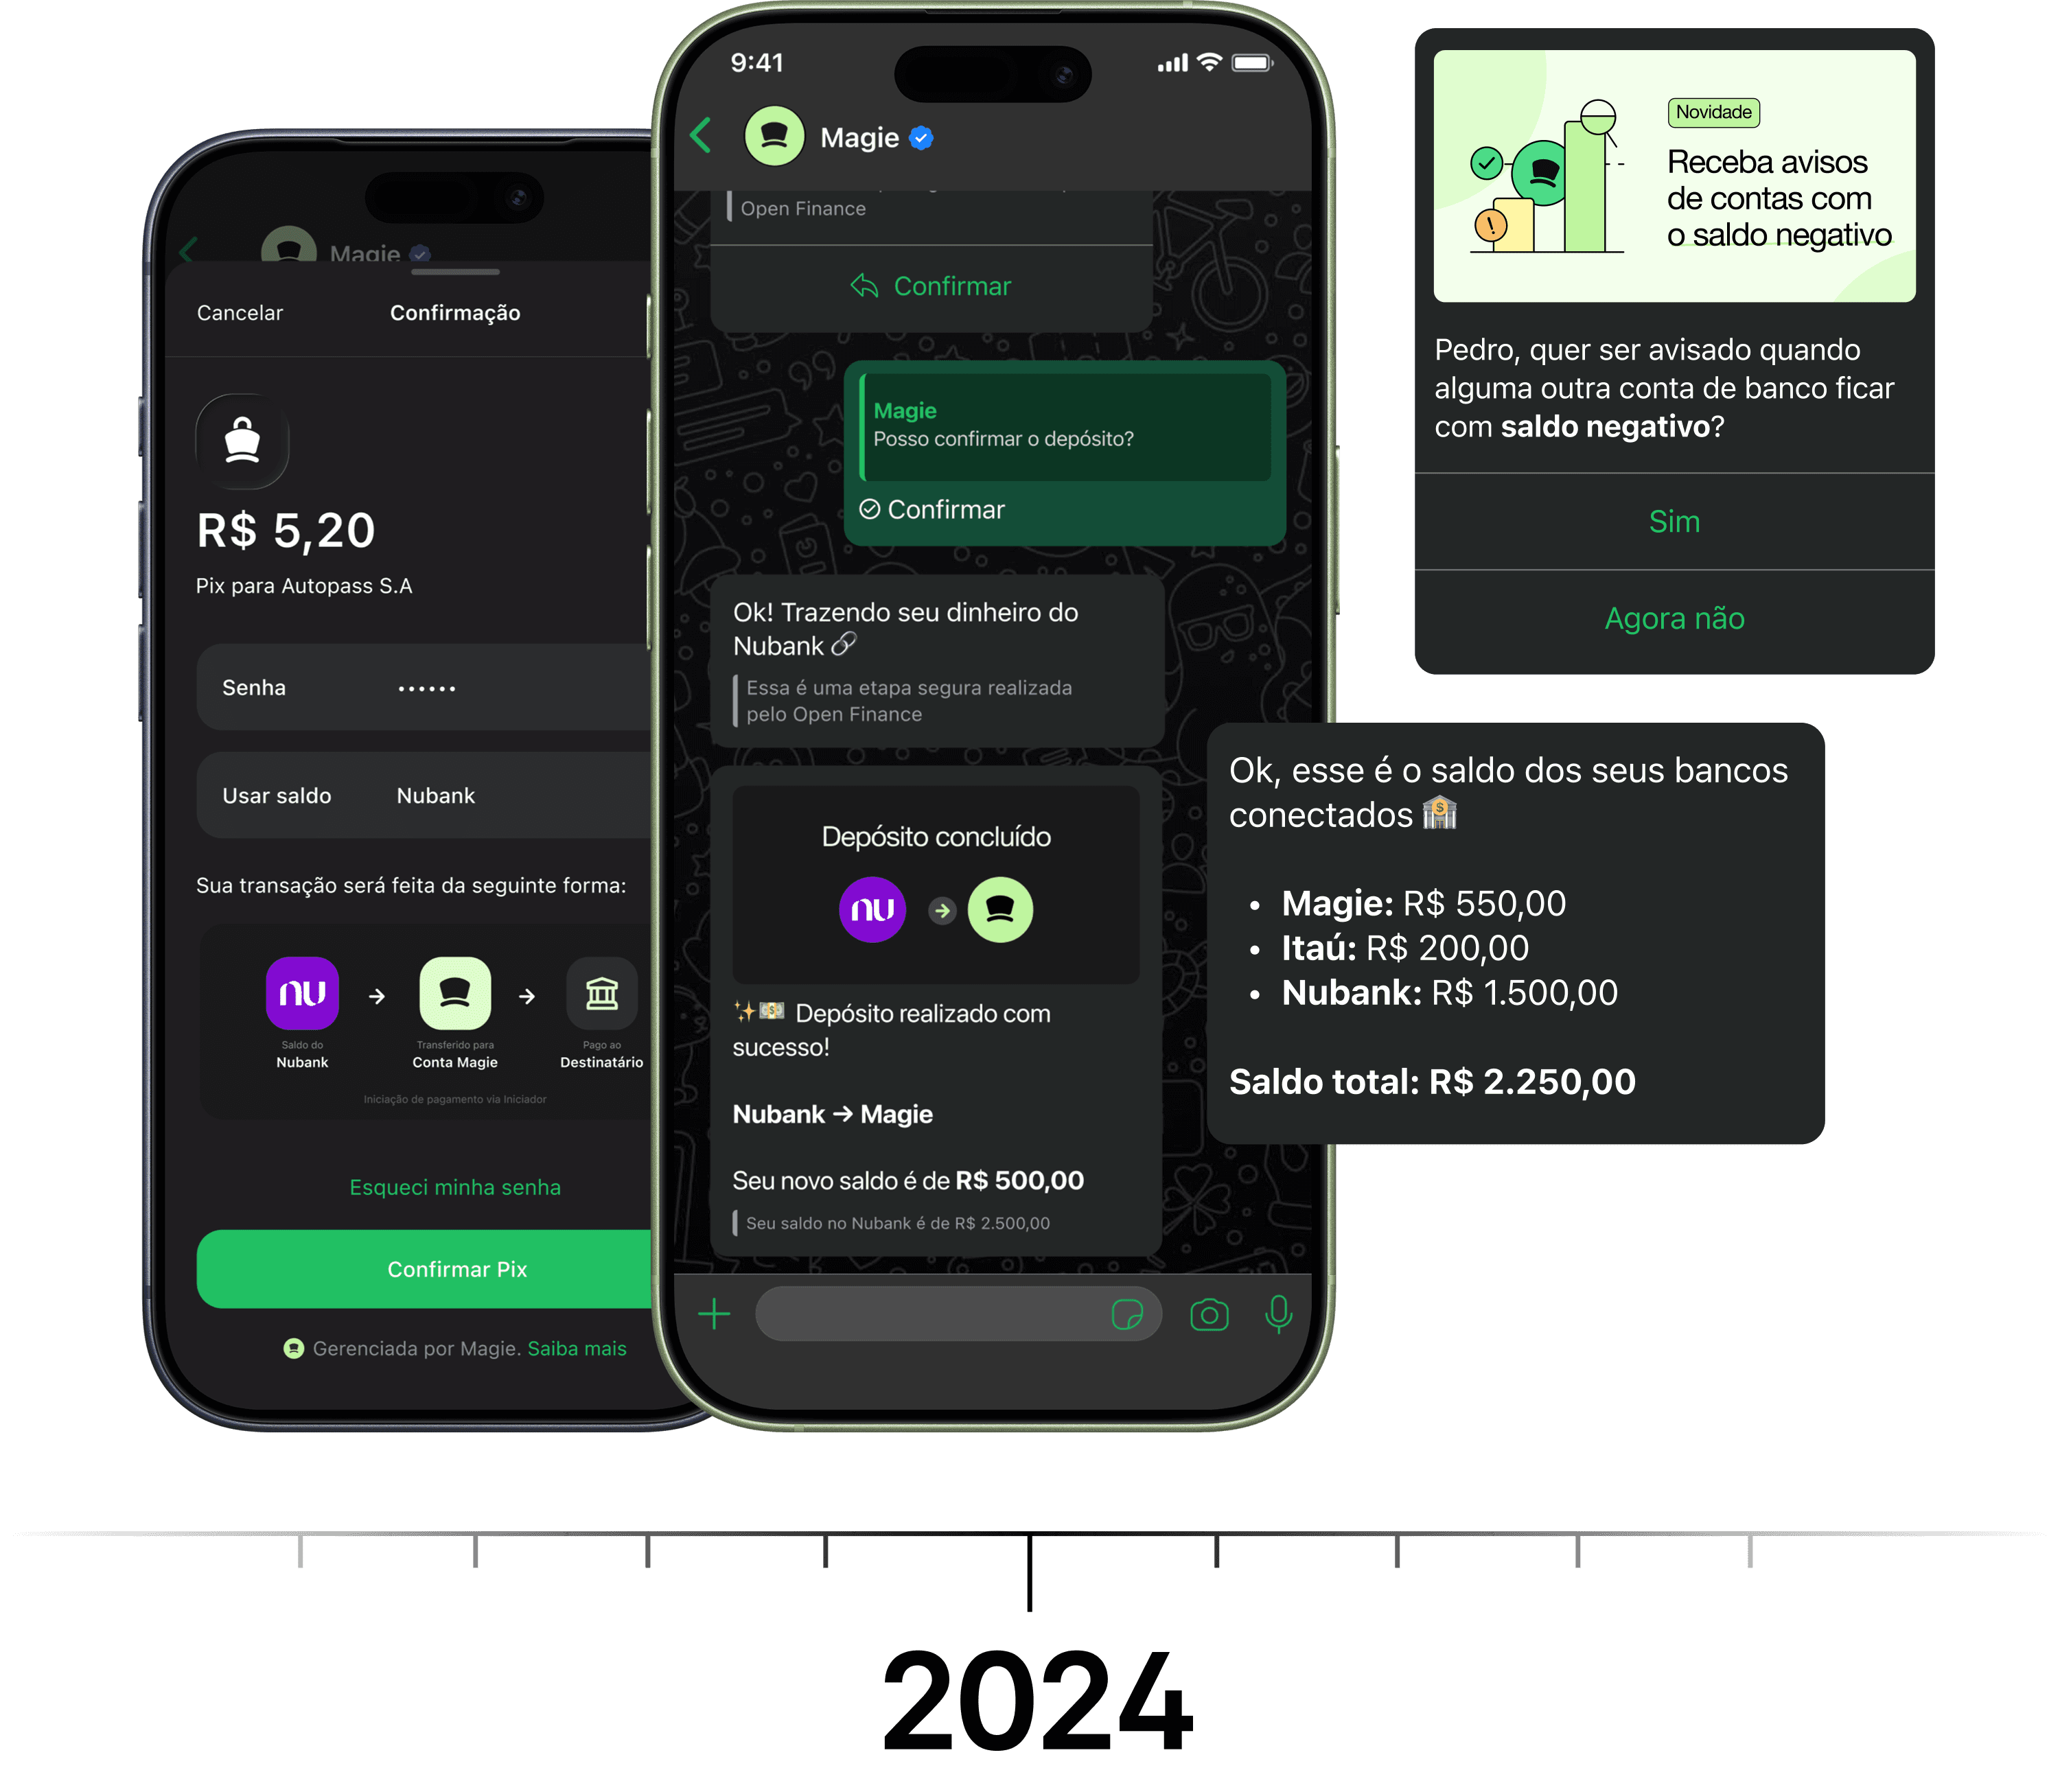
On April 23, 2024, a financial assistant launched in Brazil with no app to download. You saved a phone number, opened WhatsApp, said hello, and a few messages later you had an account.
From then on you paid boletos by sending a photo, made Pix transfers by voice note, asked for your balance the way you would ask a friend what time it is. It was invite-only, aimed at a few hundred people who made five or ten payments a day and were tired of copying codes between apps. In the closed pilot before launch, that small group had already moved about R$13 million.
Two years later the same technology runs behind the brands of banks, telecoms and retailers, in two languages and two countries, for more than a million people. This is the story of how it got there, and what design had to do at each step.
The thesis
Magie was founded by Luiz Ramalho at the end of 2023 on an observation about timing. Four things had matured in Brazil at the same moment:
Pix had made instant payments universal and free.
Open Finance had made it legal for a person to let one institution act on their accounts at another.
WhatsApp was on 200 million Brazilian phones and had just gained native features, like password entry, that made transactions inside a chat viable.
Language models had become good enough to understand intention in natural language, including audio and images.
Separately these were four trends. Together they formed a new layer between people and their money: agents that converse, understand and act. The bet was that conversation is the natural interface for money, and that the hardest problems of a challenger bank, getting someone to download an app, learn it and trust a name they have never heard, could be sidestepped by living where people already are.
I joined as part of the founding team and the sole designer. Every step below is a chapter of the same problem seen from a different angle.
From a 2023 experiment to Lux Capital's first bet in Brazil.
The first design problem was that a chat has no screens. There is no hierarchy to lean on, no place to hide a complex flow, no layout to organize information. Every confirmation, every balance, every error has to read clearly in a grey bubble sitting between a meme and a family group.
The early work was about establishing the grammar of a financial conversation: what a payment confirmation must always contain, in what order (amount, recipient, date, then the password request), how money is written, how the agent asks for one thing at a time, how it says no. Much of what later became the platform's voice rules was decided here, message by message.
The second problem was trust in an untrusted medium. A password typed into a chat keyboard is a bad idea, so the moments that carry risk moved into WhatsApp Flows, the native forms that open on top of the conversation. Authentication, confirmation, anything a regulator would want to audit, happens in a Flow. Everything a person just needs to say happens in the chat. That rule was set in the first year and never changed.
Investors read the same timing. Canary funded the pre-seed before launch. In August 2024, Lux Capital made Magie its first investment in Brazil.
2025: from MVP to a daily habit
The question for the second year was whether a WhatsApp bank was a novelty or a habit. The answer arrived in June 2025: R$1 billion transacted in the first twelve months, driven by a base that kept growing on word of mouth. Two product moves made that possible, and both were design problems as much as business ones.
The first was Open Finance built as a product. Until then the market had used Open Finance to read people's data and score them for credit. Magie made it something you use: connect the accounts you already have, then pay boletos, bills and Pix with the balance from any of them, see all your balances in one place, schedule payments, put recurring bills on automatic debit from the bank of your choice. Designing it meant making the mandatory friction of the regulation, the consent that must happen inside the other bank, read as a security signal instead of a dead end, and keeping the agent from ever printing another bank's balance on a lock screen. It was the first time the connection itself was the experience.
2025: from MVP to a daily habit
The question for the second year was whether a WhatsApp bank was a novelty or a habit. The answer arrived in June 2025: R$1 billion transacted in the first twelve months, driven by a base that kept growing on word of mouth. Two product moves made that possible, and both were design problems as much as business ones.
The first was Open Finance built as a product. Until then the market had used Open Finance to read people's data and score them for credit. Magie made it something you use: connect the accounts you already have, then pay boletos, bills and Pix with the balance from any of them, see all your balances in one place, schedule payments, put recurring bills on automatic debit from the bank of your choice. Designing it meant making the mandatory friction of the regulation, the consent that must happen inside the other bank, read as a security signal instead of a dead end, and keeping the agent from ever printing another bank's balance on a lock screen. It was the first time the connection itself was the experience.
The second was widening the door, and stress testing the limits on what the WhatsApp component library could achieve, mainly through two initiatives:
Magie+: a loyalty program built entirely in WhatsApp Flows, an app as a complement to the conversation for the things a chat does badly, like charts and reports, and a rebuilt onboarding.
Magie Split: a full splitwise experience in WhatsApp. Users can create groups and split expenses directly through the conversation.
And of course, the onboarding work where the design job gets least glamorous and most important: writing every refusal and error a person can hit when opening a regulated account, from a failed security check to a fraud-risk block, so that being told no still feels like being treated as an adult. By the end of the year the base had passed 400,000 users and R$2 billion moved.
2026: MagieOS, the platform behind other brands
By early 2026 the company had learned something the numbers only hinted at. Every organization with customers on WhatsApp wanted what Magie had built, and none of them wanted to build it.
In January, Magie raised US$5 million, passing US$10 million since founding, and announced the move: the same technology offered whitelabel, running under the client's brand, with the consumer product kept alive as the laboratory where the platform keeps evolving. Banks, a telecom, a retailer's fintech, a bank in another country, each deploying its own agent on Magie's rails.
2026: MagieOS, the platform behind other brands
By early 2026 the company had learned something the numbers only hinted at. Every organization with customers on WhatsApp wanted what Magie had built, and none of them wanted to build it.
In January, Magie raised US$5 million, passing US$10 million since founding, and announced the move: the same technology offered whitelabel, running under the client's brand, with the consumer product kept alive as the laboratory where the platform keeps evolving. Banks, a telecom, a retailer's fintech, a bank in another country, each deploying its own agent on Magie's rails.
Underneath all three sat a change in how I work. With one product, the designer decides and engineering implements. With a platform, the designer's job is to make the decisions transmissible: written as rules, structured as data, testable on every prompt version. Design stopped being a set of screens and became part of the infrastructure.
My role across the arc
I was the founding designer and remained the only one until 2026. In 2024 that meant the conversational grammar, the brand and the first journeys. In 2025 it meant Open Finance, onboarding, error language, surveys, the flows nobody sees until something goes wrong. In 2026 it meant systems: a voice tool, a conversation system, localization, and the go-to-market material that explains to a bank why a partner model beats building from scratch. Throughout, I worked directly with engineering, with the team that tunes what the agents say, and with GTM, in a company small enough that the same person writes the error message and the customer story.
Where it stands
Magie today describes itself as the first financial assistant in Brazil on WhatsApp, with more than R$2.5 billion transacted and half a million people using it every day. The user base crossed one million in 2026. The consumer product that started as an invite-only tool for heavy payers is now the proving ground for a platform that lets other organizations offer banking inside a conversation, in their own voice, without writing a line of it.
My role across the arc
I was the Founding Designer, and in 2024 that meant the conversational grammar, the brand and the first journeys.
In 2025 it meant Open Finance, onboarding, error language, surveys, the flows nobody sees until something goes wrong.
In 2026 it meant systems: a voice tool, a conversation system, localization, and the go-to-market material that explains to a bank why a partner model beats building from scratch.
Throughout, I worked directly with engineering, with the team that tunes what the agents say, and with GTM, in a company small enough that the same person writes the error message and the customer story.
Where it stands
Magie today describes itself as the first financial assistant in Brazil on WhatsApp, with more than R$2.5 billion transacted and half a million people using it every day. The user base crossed one million in 2026. The consumer product that started as an invite-only tool for heavy payers is now the proving ground for a platform that lets other organizations offer banking inside a conversation, in their own voice, without writing a line of it.
The bet from 2023 has held. The channel was never the point. The intelligence behind it was, and the two years since launch were spent making that intelligence sound like a bank people trust, then like several banks at once.